AML Laws and Regulations for Finance Companies in Singapore
In a Nutshell
A finance company is a public company that holds a valid licence granted by the Monetary Authority of Singapore under the Finance Companies Act 1967 to conduct financing business in Singapore. It may accept deposits and provide credit facilities, subject to the restrictions in the Act. These restrictions include limitations on accepting deposits repayable on demand by cheque, dealing in foreign currency, gold or precious metals, and holding foreign currency securities, subject to the exemptions provided under the Act. Its predominantly focused on deposits and lending.
The rulebook a finance company works to is MAS Notice 824 and its Guidelines. They set the risk based approach, customer due diligence, the wire transfer travel rule, enhanced measures for politically exposed persons and higher risk situations, reliance on third parties, record keeping and suspicious transaction reporting.
Singapore’s 2024 assessment places finance companies in the lower money laundering risk band, because they offer a limited range of straightforward products, deal mainly with domestic customers. Cash handling is the main feature to watch.
Around this core sit the criminal and sanctions statutes, the national risk assessments, the Finance Companies Act that licenses the sector, and the FATF standards. Each instrument that follows is explained plainly, with a pointer to the exact source it comes from.
AML Laws and Regulations for Finance Companies in Singapore
A finance company sits between a bank and a specialist lender: it accepts deposits and provides financing, subject to the restrictions in the Finance Companies Act 1967. It cannot accept deposits repayable on demand by cheque, draft or order drawn by a depositor, or deal in foreign currency, gold or other precious metals.
These statutory restrictions contribute to the sector’s predominantly domestic business profile, but they do not mean that a finance company has no exposure to cross border or foreign currency related risks where other applicable activities or transactions are involved.
This guide sets out the laws and regulations that apply to a finance company in Singapore, from the criminal statutes that make money laundering an offence to the detailed rulebook the Monetary Authority of Singapore (MAS) enforces on finance company business.
The framework is best read in layers. The criminal and sanctions laws sit at the base. Above them is the instrument a finance company works with every day, MAS Notice 824, together with its Guidelines. Alongside these run Singapore’s national risk assessments, the Finance Companies Act that licenses the sector, and the FATF standards behind the whole regime.
Singapore's Finance Companies at a Glance
The 2024 Money Laundering National Risk Assessment reported three finance companies operating in Singapore with combined assets of over S$17.5 billion based on the data period used for the assessment, that provide fixed and savings deposits and credit facilities to individuals and corporates (Money Laundering National Risk Assessment 2024, chapter 7.15).
A finance company is licensed under the Finance Companies Act 1967. It cannot accept deposits that are repayable on demand by cheque, draft or order drawn by the depositor. This restriction distinguishes finance company deposit taking from the demand deposit facilities typically associated with current accounts. These restrictions contribute to the sector’s predominantly domestic business profile and lower cross border money laundering exposure (ML NRA 2024, chapter 7.15).
Risk rating: the sector is assessed in the lower money laundering risk band, with a moderately lower ML threat and lower vulnerability (ML NRA 2024, chapter 7.15).
Core AML Laws and Regulations for Finance Companies in Singapore
These laws and regulations form the legal foundation for a finance company’s AML/CFT and sanctions obligations. They establish offences and prohibitions relating to money laundering, terrorism financing and dealings involving designated persons or property, together with specific disclosure, asset freezing and other obligations where applicable. They should be read alongside the sector specific requirements imposed by MAS Notice 824.
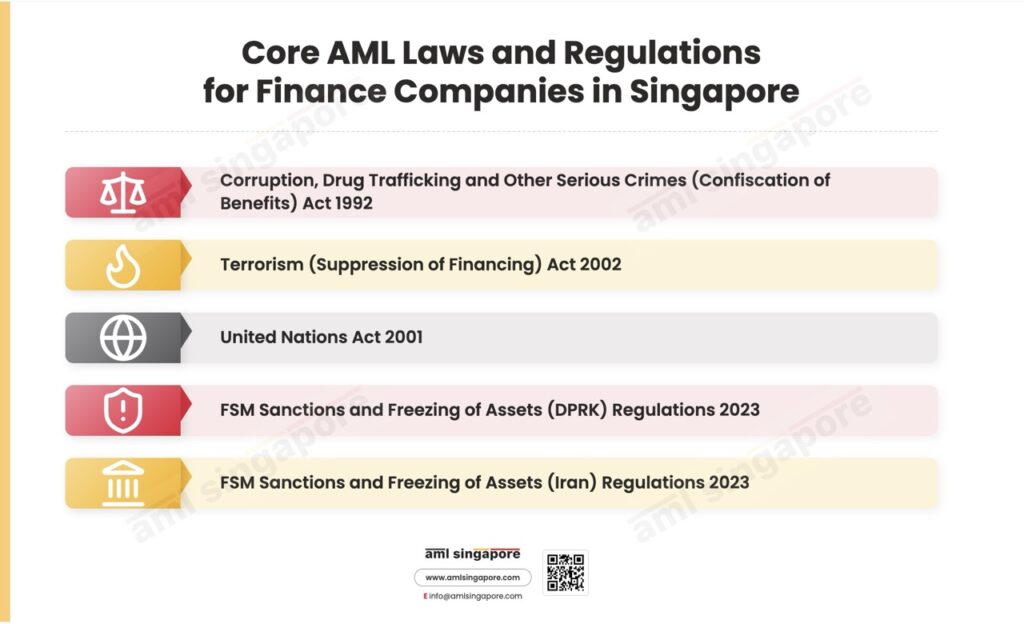
The Corruption, Drug Trafficking and Other Serious Crimes (Confiscation of Benefits) Act 1992
The CDSA establishes Singapore’s principal money laundering offences and provides for the confiscation of criminal benefits. Section 45 requires a person who, in the course of a business or employment, knows or has reasonable grounds to suspect that any property represents proceeds of, or was used or is intended to be used in connection with, drug dealing or criminal conduct to make the required disclosure to the Suspicious Transaction Reporting Office as soon as reasonably practicable. Section 57 also contains the offence of tipping off in specified circumstances.
The Terrorism (Suppression of Financing) Act 2002
Under the TSOFA, it is an offence to provide or collect property for terrorist purposes and to deal with property that is owned or controlled by terrorists or terrorist entities in circumstances prohibited by the Act. The Act also contains disclosure obligations where a person has information or suspicion concerning terrorist financing or terrorist property. A finance company should therefore maintain appropriate controls to identify and prevent prohibited dealings, including screening and escalation processes, while recognising that screening is a control used to meet applicable legal and regulatory obligations rather than the statutory obligation itself.
The United Nations Act 2001
The United Nations Act 2001 provides the statutory basis for Singapore to give effect to certain United Nations Security Council measures through subsidiary legislation. Singapore’s sanctions framework also includes financial sector regulations made under the Financial Services and Markets Act 2022. A finance company must therefore comply with the particular sanctions legislation and MAS requirements applicable to it, depending on the relevant designated person, jurisdiction, activity or sanctions measure.
The Financial Services and Markets (Sanctions and Freezing of Assets of Persons, DPRK) Regulations 2023
Made under the Financial Services and Markets Act 2022, these regulations impose financial sector measures relating to the Democratic People’s Republic of Korea (DPRK), including prohibitions on dealings with designated persons and requirements concerning designated property. Where the regulations apply, a finance company must comply with the applicable asset freezing, dealing and reporting requirements. The finance company should therefore maintain controls to identify designated persons and property and act promptly when a potential match is identified.
The Financial Services and Markets (Sanctions and Freezing of Assets of Persons, Iran) Regulations 2023
The Iran regulations, also made under the Financial Services and Markets Act 2022, give effect to specified financial measures relating to United Nations Security Council Resolution 2231 (2015). Where applicable, a finance company must comply with the prohibitions, asset freezing requirements and other obligations imposed by the regulations. Screening customers, beneficial owners and relevant connected parties is an important control for identifying potential sanctions exposure, but the applicable statutory requirements should be applied according to the specific prohibition or obligation concerned.
Overarching AML Laws and Regulations Applicable to Finance Companies in Singapore
These instruments cut across the whole regime and give a finance company the practical means to discharge its reporting duties and to recognise terrorism financing when it surfaces in a deposit or a loan.
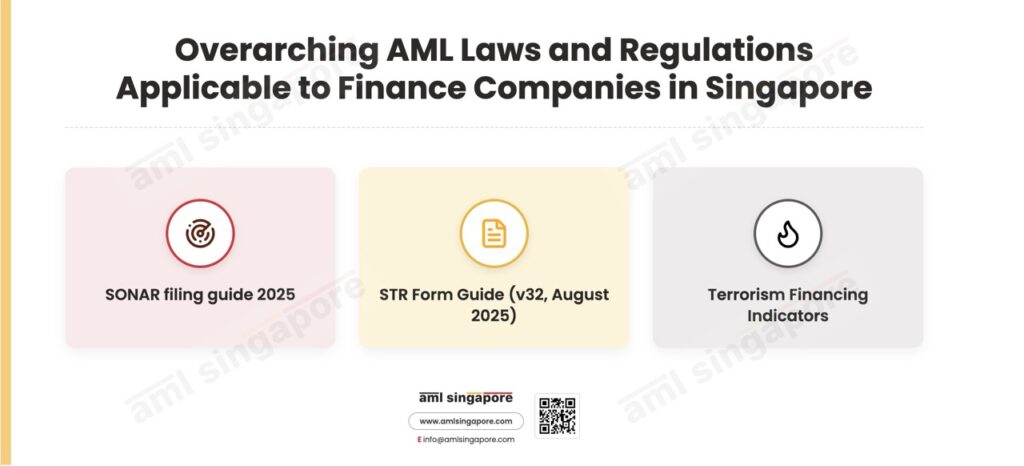
Getting Started with SONAR, for STR Filers (2025)
SONAR is the STRO Online Notices and Reporting platform through which a finance company lodges its suspicious transaction reports electronically. It guides a filer through registration, the setting of user roles and the act of submission. SONAR is the STRO’s electronic platform for submitting suspicious transaction reports. Finance companies subject to the applicable reporting requirements use the platform to submit STRs electronically. A finance company’s compliance function depends on it to file promptly and to keep proof of each report.
Form Guide for the STR Form (Version 12 August 2025)
A section by section guide to the current suspicious transaction report form. It works through each entry, from the details of the reporting firm to the narrative of why suspicion arose, and it expects a distinct internal reference on every submission. For a finance company it is the reference a compliance officer uses to put together a full, well supported report on a questionable deposit, repayment or loan.
Terrorism Financing Indicators
A red flag reference from STRO that groups terrorism financing indicators into due diligence anomalies, unusual movement of funds and transactions without economic purpose. For a finance company it helps flag terrorism financing at onboarding or during an account relationship, such as a loan repaid by an unrelated third party, and helps firms identify potential terrorism financing risks and assess whether further investigation, escalation or reporting is required.
National Risk Assessments Applicable to Finance Companies in Singapore
Singapore publishes national assessments of its money laundering, terrorism financing and proliferation financing risks. These assessments provide important risk information that a finance company should consider when conducting and updating its own risk assessment. The 2024 Money Laundering National Risk Assessment assesses the finance company sector as having a lower relative money laundering risk, while identifying cash transactions as a relevant risk feature for the sector.
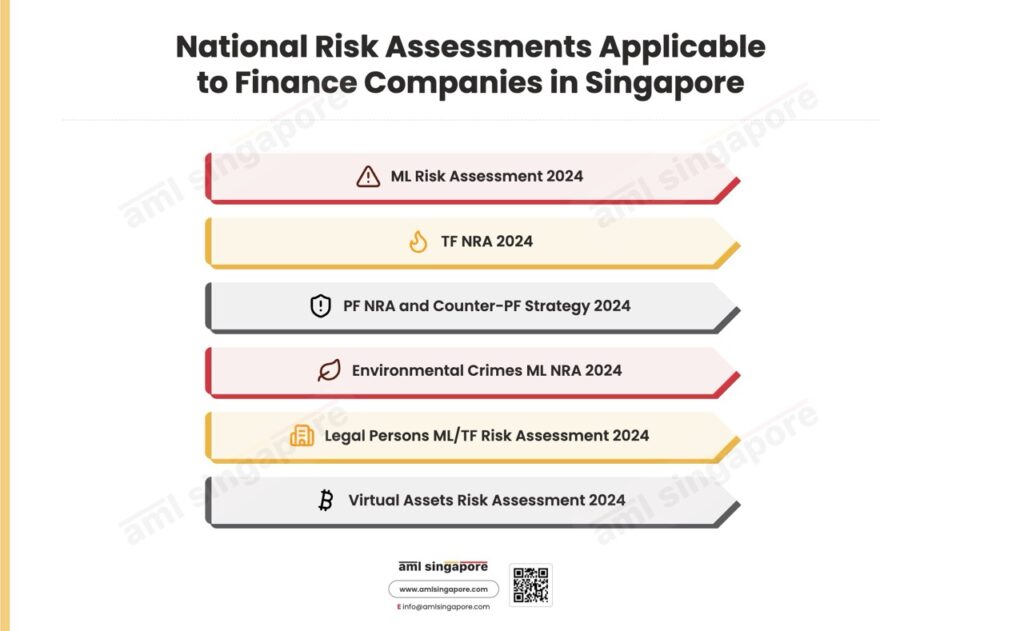
Money Laundering National Risk Assessment Singapore 2024
The Money Laundering National Risk Assessment 2024 assesses finance companies as a lower money laundering risk sector. It identifies the sector’s relatively limited range of products and predominantly domestic business as factors contributing to its lower risk profile. The assessment also notes that finance company customers are more likely than bank customers to transact in cash. These findings are relevant risk factors for a finance company’s own enterprise wide and sector risk assessment.
Terrorism Financing National Risk Assessment 2024
The Terrorism Financing National Risk Assessment 2024 considers the channels and vulnerabilities relevant to Singapore’s terrorism financing risk. The Terrorism Financing National Risk Assessment 2024 provides risk information relevant to Singapore’s financial sector. Finance companies should consider relevant findings when assessing their own terrorism financing exposure and controls.
Proliferation Financing National Risk Assessment and Counter PF Strategy 2024
The Proliferation Financing National Risk Assessment and Counter PF Strategy 2024 identify risks including sanctions evasion, the misuse of legal persons and trade involving proliferation sensitive goods. These findings may be relevant to a finance company’s proliferation financing risk assessment, particularly where its customers, transactions or activities present corresponding risk factors.
Environmental Crimes Money Laundering National Risk Assessment (May 2024)
A thematic study covering how the proceeds of environmental crime, from the illegal wildlife trade to illegal logging, are washed through the financial system. Its relevance to a finance company is limited, arising only where a borrower’s funds may derive from such activity.
Money Laundering and Terrorism Financing Risk Assessment of Legal Persons (2024)
This assessment examines the risks of legal persons being misused for money laundering and terrorism financing and highlights vulnerabilities associated with ownership and control structures. It is particularly relevant to a finance company dealing with corporate borrowers, holding companies or other legal persons and reinforces the importance of identifying and verifying the natural persons who ultimately own or control the customer.
Virtual Assets (Digital Payment Tokens) Risk Assessment (2024)
This assessment considers the money laundering and terrorism financing risks associated with virtual asset activity in Singapore. Its direct relevance to a finance company depends on the firm’s products, customers and exposure to virtual asset activity. Where a customer’s source of funds or wealth is linked to virtual assets, the finance company should assess the associated risks and apply appropriate due diligence and monitoring measures.
Finance Company Sector ML/TF Risk Snapshot
Money laundering: lower risk band, with a moderately lower ML threat and lower vulnerability, because the sector offers a limited, straightforward product range (ML NRA 2024, chapter 7.15).
Main feature to watch: cash, since finance company customers are more likely than a bank’s to transact in cash, though the business is largely domestic and cross border risk is low (ML NRA 2024, chapter 7.15).
Controls: the AML/CFT requirements mirror those applied to banks, and MAS has not observed key weaknesses in the sector’s controls (ML NRA 2024, chapter 7.15).
Proliferation and terrorism financing: mostly indirect, through corporate borrowers with opaque ownership (PF and TF NRAs 2024).
Sector Specific Guidance Applicable to Finance Companies in Singapore
This is the core of a finance company’s obligations. MAS supervises finance companies under the applicable Singapore financial services legislation and issues applicable regulatory requirements and supervisory guidance. The binding requirements applicable to a finance company should be distinguished from MAS guidelines, information papers and other supervisory material. The material divides into common instruments that apply across financial institutions and the specific instruments written for the sector, led by MAS Notice 824 and its Guidelines.
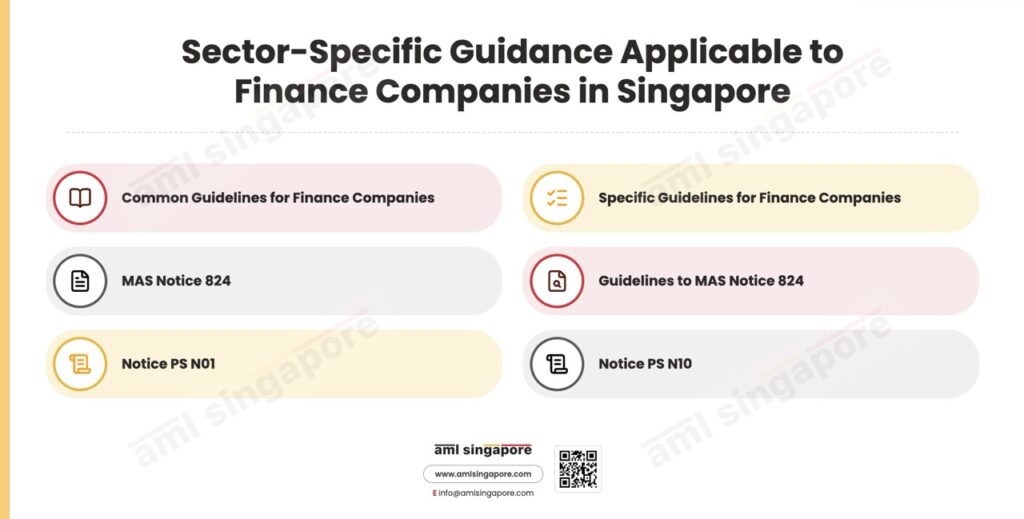
Common Guidelines for Finance Companies
These MAS instruments apply across financial institutions and shape how a finance company designs its controls. They do not replace Notice 824; they explain MAS’s supervisory expectations on themes such as source of wealth, transaction monitoring, misuse of legal persons, sanctions and audit.
The Financial Services and Markets Act 2022
The Financial Services and Markets Act 2022 provides important statutory powers for MAS to regulate and supervise financial institutions in areas including money laundering and terrorism financing. Section 16 empowers MAS to issue directions or make regulations concerning financial institutions for the prevention of money laundering and terrorism financing. The Act also provides the statutory framework for certain financial sector sanctions regulations and MAS’s supervisory and enforcement powers. A finance company should therefore read Notice 824 together with the applicable provisions of the FSM Act and its subsidiary legislation.
Circular AMLD 01/2018: Use of MyInfo and CDD for Non Face to Face Business Relations
This circular accepts the Government’s MyInfo service as a reliable and independent source of a customer’s core identity data. A finance company onboarding a MyInfo user, common where a deposit or a loan is opened online, can verify from that data rather than gathering documents afresh, subject to the circular’s safeguards for the impersonation risk that arises where MyInfo is not used.
Circular AMLD 01/2022: Non Face to Face Customer Due Diligence Measures
This circular sets MAS’s expectations for onboarding people and entities without face to face contact, which matters as finance companies open deposits and process loan applications through digital channels. It warns that a video or selfie check alone may fall short, recommends a second independent channel for higher risk customers, and expects any onboarding technology to be assessed by the firm and approved by its board and senior management.
Circular AMLD 02/2023: ML/TF Risks in the Wealth Management Sector
Aimed at wealth management, this circular reaches a finance company only at the margins, where it serves a high net worth depositor or a corporate customer with layered ownership. Even there, its themes hold: firmer board oversight, a fresh look at due diligence and quality assurance, and seeing past holding vehicles to the real beneficial owners, and treating a customer who withdraws rather than answer questions as a reason to weigh a report.
Circular AMLD 08/2024: Establishing the Sources of Wealth of Customers
This circular sets out how a firm should establish a customer’s source of wealth before business begins. For a finance company, it matters most on a large deposit or a substantial credit facility: the firm should take reasonable steps to establish the source of wealth, corroborate it under tests of materiality, prudence and relevance, and escalate what it cannot substantiate.
Circular AMLD 05/2026: Risk Proportionate Source of Wealth Establishment
A 2026 circular that dials source of wealth work back to what the risk warrants. MAS wants the effort kept effective, efficient and proportionate to risk, so ordinary retail depositors are not burdened. A finance company should concentrate corroboration on material or higher risk relationships, spare low risk customers repeated requests, and reserve escalation for genuine red flags.
Circular AMLD 11/2023: Ensuring Effective Detection of Sanctions Related Risks
MAS expects firms to detect and manage sanctions risk, including unilateral sanctions imposed by other jurisdictions. Risk appetite is a board matter, and the circular sets out a lookback review once a party is designated. For a finance company, the practical effect is disciplined screening of customers and connected parties, and a review of live accounts and loans when a name is listed.
Circular AMLD 12/2024: Audit of AML/CFT Policies, Procedures and Controls
These circular addresses the independent audit that forms a firm’s third line of defence. A finance company must maintain the internal AML/CFT policies, procedures and controls required by the applicable regulatory framework, including appropriate independent audit arrangements where required. The scope and frequency of independent testing should be proportionate to the firm’s size, complexity and risk profile.
Strengthening AML/CFT Controls on Misuse of Legal Persons and Complex Structures (August 2023)
Built on inspection findings, this MAS paper portrays firms that let troubling flows pass through trusts, foundations and stacked corporate layers. Its case studies show plainly where firms fell short of identifying the true beneficial owner. A finance company lending to companies and holding structures should measure itself against it and be sure it has traced the natural persons behind a corporate borrower.
AML/CFT Supervisory Expectations from Recent Inspections (October 2024)
Drawn from its recent inspections, this paper sorts MAS’s expectations into five areas: treating multiple nationalities and investment migration ties as risk factors, catching red flags in documents, testing whether a customer’s source of wealth holds together, backing a report or an exit with real mitigation, and moving customer information across business lines. Each bears on how a finance company onboards and reviews an account.
Best Practices in Relation to Risks in Wealth Management (May 2025)
An industry paper for firms that serve wealthy customers, drawing together case studies on private investment companies, trusts and remote onboarding. Its reach into a finance company is limited to the occasional high value depositor or complex corporate borrower, but where an adviser or bank sits alongside the relationship, the finance company must still satisfy its own due diligence duties on the customer and its beneficial owners.
Effective Practices to Detect and Mitigate the Risk from Misuse of Legal Persons (June 2019)
This MAS paper concerns guarding against shell and front companies for the length of a relationship. It offers multi factor risk assessment, red flag lists, network link analysis and staff training, and it makes the point that one red flag rarely decides a case by itself. A finance company lending to corporate customers should weigh several signals together before it acts.
Guidance for Effective AML/CFT Transaction Monitoring Controls (September 2018)
This paper consolidates the transaction monitoring expectations MAS has built up over its inspections. A finance company sees a steadier, mostly domestic flow of deposits, repayments and drawdowns, so the guidance is applied proportionately, but its themes, tuning what to look for, keeping data clean and recording how alerts are handled, still shape how a finance company monitors account activity.
Guidance to Capital Markets Intermediaries on Enhancing AML/CFT Frameworks and Controls (January 2019)
Written for capital markets intermediaries, this MAS guidance on governance, risk awareness and execution binds a finance company directly only where the same group also holds a capital markets services licence. For other finance companies it is persuasive good practice on board accountability, the three lines of defence and how a firm resources its AML/CFT programme.
Guidelines on Risk Management Practices, Internal Controls (July 2024)
A prudential guideline setting out what MAS looks for in a firm’s control environment and its business process controls. It touches customer due diligence only lightly and defers to the AML/CFT notices for the detail, so for a finance company it supplies the internal controls scaffolding, from segregation of duties to management reporting, that the AML/CFT programme is built around rather than a source of AML duties in itself.
Guidelines on Provision of Digital Advisory Services (October 2018)
A conduct guideline aimed at digital and robo advisory services. It bears on a finance company only where it gives automated advice through a digital platform. Its AML/CFT relevance is slight: a reminder that a remote channel still needs proper ML/TF controls and must handle the impersonation risk of taking on a customer who is never met in person.
Sound Practices to Counter Proliferation Financing (August 2018)
Informed by MAS’s thematic reviews, this paper deals with proliferation financing connected to DPRK and Iran sanctions evasion. It sets out how firms should tighten controls, keep watch over higher risk customers and counterparties, and spot typologies such as shell companies fronted by nominee directors. It reaches a finance company whose corporate borrowers may carry links to higher risk jurisdictions.
Strengthening Financial Institutions' CFT Controls (May 2023)
Rooted in an industry wide survey, this MAS information paper focuses on countering the financing of terrorism. It restates the duty to freeze and report designated party assets and sets expectations for screening, escalation and prompt, good quality reporting, each of which a finance company applies to its customers and their connected parties.
Specific Guidelines for Finance Companies
These are the principal MAS instruments relevant to a finance company’s AML/CFT framework. MAS Notice 824 is the sector specific AML/CFT notice for finance companies, and the Guidelines to Notice 824 explain MAS’s expectations on applying the Notice. Other MAS notices or regulatory instruments apply only where the finance company carries on additional regulated activities to which those instruments apply.
MAS Notice 824 on Prevention of Money Laundering and Countering the Financing of Terrorism, Finance Companies
MAS Notice 824 is the principal AML/CFT notice applicable to finance companies licensed under the Finance Companies Act 1967. The Notice is issued under section 16 of the Financial Services and Markets Act 2022 and applies to finance companies within its scope. The Notice is issued under the Financial Services and Markets Act 2022 and sets out requirements relating to risk assessment, customer due diligence, enhanced due diligence, reliance, wire transfers, record keeping, suspicious transaction reporting and internal AML/CFT controls. The AML/CFT framework was strengthened with amendments taking effect from 1 July 2025, including requirements relating to proliferation financing risk assessment and other changes to customer due diligence and suspicious transaction reporting.
After the underlying principles, the Notice requires a finance company to identify, assess and understand its money laundering and terrorism financing risk across its customers, the countries they operate in, and its products, services and channels, and to apply a risk based approach with senior management approved policies and enhanced measures where risk is higher. It must assess new products, practices and technologies before launch.
Customer due diligence is a core requirement. A finance company must not maintain anonymous or fictitious name accounts and must perform customer due diligence in the circumstances specified in Notice 824, including when establishing business relations, undertaking applicable occasional transactions, carrying out specified cross border wire transfers for customers without an account, where there is suspicion of money laundering or terrorism financing, or where the firm has doubts about previously obtained identification information. The finance company must identify and verify the customer and relevant persons acting on its behalf, identify and verify the beneficial owner and understand the ownership and control structure of a legal person. A 25% ownership threshold may be relevant when identifying beneficial ownership, but it should not be treated as an automatic substitute for assessing ultimate ownership or control.
The Notice adopts a risk based approach to customer due diligence. Simplified measures may be applied only where the relevant conditions and lower risk circumstances permit. Enhanced due diligence is required in the circumstances specified by the Notice, including relationships involving politically exposed persons and other higher risk situations. This includes obtaining and, where appropriate, corroborating information on source of wealth and source of funds, obtaining senior management approval where required and applying enhanced ongoing monitoring. Geographic risk, including exposure to jurisdictions identified as presenting higher risk, should be considered as part of the firm’s overall risk assessment rather than treated as an automatic trigger in every case. Where reliance on a third party is permitted, the finance company remains responsible for meeting its applicable AML/CFT obligations.
The remaining requirements cover record keeping, suspicious transaction reporting and the governance of the AML/CFT framework. The finance company must retain relevant records for the period required by the Notice and maintain appropriate policies, procedures and controls, including arrangements for AML/CFT compliance, independent audit and staff training. Where there are grounds for suspicion, the applicable disclosure must be made in accordance with the CDSA and MAS requirements, while the firm must also take care not to disclose information in circumstances that would constitute tipping off. The statutory CDSA standard is that a disclosure should be made as soon as reasonably practicable, while MAS requirements and guidance set out additional expectations concerning the timeliness and process for STR submission.
Guidelines to MAS Notice 824 (the primary guidance for finance companies)
The Guidelines to Notice 824 provide MAS’s guidance on the application of the requirements in Notice 824. They are not legislation or binding requirements in the same way as the Notice itself, but they explain MAS’s supervisory expectations and provide practical guidance on how a finance company should implement its AML/CFT framework. A finance company should therefore read the Guidelines alongside the corresponding provisions of Notice 824 and apply them proportionately to its risk profile.
The Guidelines open with the sector’s risk profile, which is lighter than a bank’s but not negligible. A finance company takes deposits and lends, so its exposure sits in cash placement, in the layering of funds through repayments and drawdowns, and in corporate borrowers whose ownership is unclear. The Guidelines address proliferation financing risk as part of the finance company’s broader AML/CFT risk-management framework and should be read together with the applicable sanctions legislation and other requirements concerning proliferation financing.
On the risk-based approach, a finance company must assess its money laundering and terrorism financing risk not only account by account but on an enterprise wide basis, taking in its products, its channels and its customer types, and including overseas operations where it is part of a financial group. The enterprise wide assessment must be approved by senior management, should combine qualitative and quantitative analysis, must incorporate the findings of Singapore’s national risk assessments, and should be refreshed when a material change occurs, such as launching a new deposit or lending product.
The customer due diligence chapter explains identification and verification of customers, persons acting on their behalf, connected parties and beneficial owners. It also explains how a finance company should understand the ownership and control structure of a legal person and identify the natural person or persons who ultimately own or control the customer. A 25% ownership threshold may be relevant to the ownership analysis, but it should not be treated as the complete legal test for beneficial ownership. The Guidelines also explain the applicable occasional transaction and cross border wire transfer requirements, non face to face onboarding and ongoing monitoring, including attention to complex, unusually large or unusual transactions that have no apparent economic or lawful purpose.
The enhanced due diligence guidance explains the treatment of politically exposed persons and other higher risk situations. It distinguishes source of wealth, which concerns the origin of a customer’s overall wealth, from source of funds, which concerns the origin of funds involved in a particular transaction or relationship. Where enhanced due diligence is required, the finance company should take appropriate steps to establish and, where necessary, corroborate this information in proportion to the risk, obtain the required senior management approval and conduct enhanced ongoing monitoring. The firm should also maintain appropriate screening and escalation controls for sanctions and other relevant risks and take the action required under the applicable sanctions legislation where a potential or confirmed match is identified.
The remaining chapters cover reliance, wire transfers, record keeping, suspicious transaction reporting and the governance of the AML/CFT framework. The finance company remains responsible for meeting its AML/CFT obligations where reliance on another party is permitted. The wire transfer requirements address the information that must accompany applicable cross border wire transfers. Under the CDSA, a suspicious transaction disclosure must be made as soon as reasonably practicable. MAS requirements and guidance also set out expectations concerning the timely submission of STRs, including a five business day expectation after suspicion is established, subject to the applicable exceptions. The proliferation financing requirements should also be read together with the applicable sanctions legislation and require appropriate controls for identifying and responding to proliferation financing risks. Throughout, the Guidelines emphasise a risk based and proportionate approach.
MAS Notice PS N01 (Specified Payment Services)
Notice PS N01 is the AML/CFT notice for licensed payment service providers under the Payment Services Act. It reaches a finance company only where the same firm also holds a payment services licence and carries on a specified payment service, such as domestic or cross border money transfer. Where the finance company itself is authorised or otherwise subject to the Payment Services Act regime for a relevant payment service, the applicable payment services AML/CFT requirements must be considered alongside the requirements applicable to its finance-company business. Notice 824 remains relevant to the finance company activities within its scope.
MAS Notice PS N10 (Exempt Payment Service Providers)
Notice PS N10 sets the AML/CFT requirements for persons exempt from holding a payment services licence, such as a bank or finance company that provides a payment service under an exemption. Notice PS N10 is relevant where an entity is exempt from holding a payment services licence but is nevertheless subject to the applicable AML/CFT requirements for the exempt payment service. A finance company should determine whether it falls within the relevant exemption and regulatory scope based on the payment service it provides.
Finance Company May Do, And the Limits That Shape Its Risk
The sector’s risk is shaped by what the Finance Companies Act allows and forbids. The table below sets the permitted activities against the licensing restrictions that keep the sector small, secured and domestic.
What a finance company may do | What the Finance Companies Act restricts |
Take fixed and savings deposits | It cannot offer a deposit account repayable on demand by cheque, draft or order, so it holds no current accounts |
Lend to individuals and businesses | Provide financing to individuals and businesses, subject to the Finance Companies Act and applicable regulatory requirements, including facilities such as hire purchase, housing finance and business finance. |
Serve a mainly domestic customer base | It cannot deal in any foreign currency, gold or other precious metals |
Hold Singapore dollar assets | It cannot acquire foreign currency denominated stocks, shares or debt securities beyond set limits |
Move funds by wire transfer | It applies the travel rule to a cross border wire transfer above S$1,500, carrying originator and beneficiary information |
Allied Laws and Guideline Applicable to Finance Companies in Singapore
These statutes are not primarily AML instruments, but each supports the regime: some license and govern finance companies, others give investigators their powers, and others create the predicate offences and proliferation controls a finance company screens against.
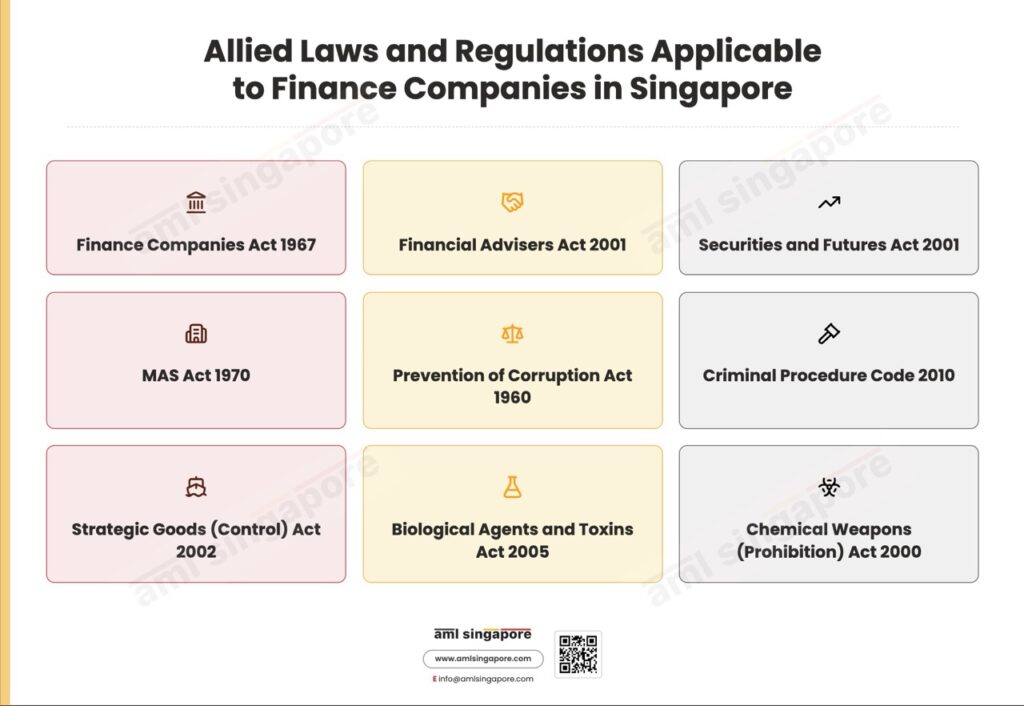
The Finance Companies Act 1967
The statute that constitutes the sector. It requires a company to be licensed under section 6 to carry on financing business, and it draws the boundaries that define the sector: no current accounts repayable on demand, no dealing in foreign currency, gold or precious metals, and no foreign currency securities beyond limits. Holding that licence is what brings a firm within Notice 824.
The Financial Advisers Act 2001
The Financial Advisers Act 2001 regulates specified financial advisory activities. It becomes relevant to a finance company only where the finance company itself carries on a regulated financial advisory activity or otherwise falls within the Act and its applicable exemptions. A separate group company or representative undertaking regulated financial advisory activities does not, by itself, make the finance company subject to the Financial Advisers Act regime.
The Securities and Futures Act 2001
The Securities and Futures Act reaches a finance company where its group’s activity extends into capital markets products, so it may take on a capital markets licence and the corresponding notice for that activity. It marks the boundary between the finance company regime and the securities regime a group can straddle.
The Monetary Authority of Singapore Act 1970
The Act establishes the Monetary Authority of Singapore and provides its institutional and regulatory framework. For the specific statutory power to issue directions or make regulations concerning financial institutions for the prevention of money laundering and terrorism financing, the relevant provision is section 16 of the Financial Services and Markets Act 2022. Finance companies therefore need to read the Finance Companies Act 1967 together with the Financial Services and Markets Act 2022 and applicable MAS requirements.
The Prevention of Corruption Act 1960
The Prevention of Corruption Act 1960 establishes offences relating to corruption. Where corruption proceeds may form part of a customer’s source of funds or source of wealth, this may be relevant to a finance company’s AML/CFT risk assessment and suspicious transaction analysis.
The Criminal Procedure Code 2010
The Criminal Procedure Code 2010 contains investigative and procedural powers that may require a financial institution to provide information, documents or other assistance to the authorities. A finance company should comply with applicable lawful orders and preserve relevant records.
The Strategic Goods (Control) Act 2002
The Strategic Goods (Control) Act 2002 regulates the transfer, brokering and related activities involving strategic goods. It may be relevant to a finance company’s proliferation financing risk assessment where a customer, borrower or transaction is connected to activities involving controlled strategic goods.
The Biological Agents and Toxins Act 2005
The Biological Agents and Toxins Act 2005 regulates specified activities involving biological agents and toxins. It may be relevant to proliferation financing risk where a finance company’s customer, borrower or transaction is connected to activities prohibited by the Act.
The Chemical Weapons (Prohibition) Act 2000
The Chemical Weapons (Prohibition) Act 2000 gives domestic effect to Singapore’s obligations concerning chemical weapons and regulates specified activities involving chemical weapons. It may be relevant to proliferation financing risk where a finance company’s customer, borrower or transaction is connected to prohibited activities under the Act.
Miscellaneous Laws and Regulations Applicable to Finance Companies in Singapore
These national strategies, committee reports and typologies set the direction of Singapore’s regime and the public private partnership a finance company operates within. They carry no binding force, but they direct how MAS supervises and supply many of the typologies a finance company builds into its screening.
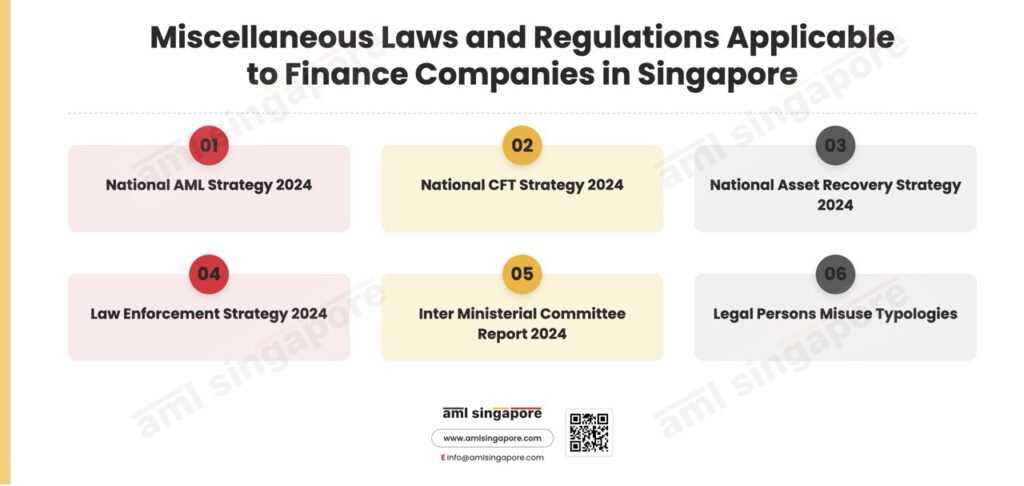
National Anti Money Laundering Strategy 2024
Singapore’s national AML strategy sets out the country’s approach to preventing, detecting and enforcing against money laundering. It provides policy context for the AML/CFT framework within which MAS regulated financial institutions, including finance companies, operate.
National Strategy for Countering the Financing of Terrorism 2024
Updated in 2024 alongside the terrorism financing risk assessment, this strategy runs across five fronts: coordinated risk identification, strong legal and sanctions frameworks, a robust regulatory regime, decisive enforcement and international partnership. It signals the direction a finance company’s terrorism financing controls should take.
National Asset Recovery Strategy 2024
Singapore’s strategy to detect, deprive and recover the proceeds of crime, citing billions recovered in recent years. A finance company is a partner in it mainly through its reporting and its cooperation with production orders, since account balances and loan proceeds can be the subject of restraint.
Singapore Law Enforcement Strategy to Combat Money Laundering (October 2024)
A joint strategy of Singapore’s money laundering investigation agencies that names focus areas and key actions and depends on two way information flows with financial institutions. It frames the enforcement backdrop a finance company supports through its reporting on suspicious deposits, repayments and loans.
Inter Ministerial Committee on Anti Money Laundering Report (October 2024)
The review conducted in the wake of a large money laundering case, recommending measures on the misuse of corporate structures, the duties of gatekeepers and better information sharing. Its themes reach a finance company whose corporate borrowers can be shell companies, and it marks the firmer supervisory stance the wider sector now sits under.
Legal Persons: Misuse Typologies and Best Practices (2018)
A typologies paper on the ways companies and partnerships get misused, giving a finance company the red flags for beneficial ownership and corporate borrower checks. It is useful where a finance company lends to a company, a partnership or a holding structure.
International Standards Applicable to Finance Companies in Singapore
Singapore’s regime is built to meet the FATF standards, and Notice 824 tracks them closely. These instruments are the least sector specific of all, yet they explain why the domestic rules look the way they do and hand a finance company the typologies and methods supervisors expect it to track.
The FATF Recommendations (updated June 2026)
The FATF Recommendations are international standards that inform Singapore’s AML/CFT and counter proliferation financing framework. They are not, by themselves, directly binding on Singaporean finance companies. The obligations applicable to a finance company arise from Singapore legislation, regulations, MAS notices and other applicable domestic requirements.
Mutual Evaluation Report of Singapore (May 2026)
The 2026 evaluation by the FATF and the Asia/Pacific Group gauges how well Singapore’s regime works on the ground. It frames supervisory expectations across the financial sector, including the proportionate expectations placed on smaller deposit taking lenders.
Methodology for Assessing Technical Compliance and Effectiveness (updated June 2026)
The instrument the FATF uses to gauge technical compliance with the Recommendations and how well a country’s system works in practice. It defines the yardstick by which Singapore, and by extension its finance companies, are measured, and it informs MAS’s supervisory expectations.
FATF Guidance on Politically Exposed Persons (Recommendations 12 and 22, 2013)
Explains how a firm should pick out politically exposed persons and subject them to enhanced due diligence: sign off by senior management, working out source of wealth and funds, and tighter ongoing monitoring, all of which a finance company brings to bear on a PEP depositor or borrower.
Guidance on Beneficial Ownership of Legal Persons (March 2023)
Guidance issued under the revised Recommendation 24 on how to obtain and verify beneficial ownership information, shaping how a finance company pins down the beneficial owners of a corporate depositor or borrower.
Best Practices on Beneficial Ownership for Legal Persons (October 2019)
A collection of country best practices for keeping beneficial ownership information adequate, accurate and up to date, backing a finance company’s use of registries and multiple sources when it identifies the controllers of a corporate customer.
Concealment of Beneficial Ownership (July 2018)
A joint FATF and Egmont Group typologies report on how criminals hide beneficial ownership through intermediaries and structures, giving a finance company the red flags to detect concealment behind a corporate borrower.
Risk Based Approach: Beneficial Ownership and Transparency of Legal Arrangements (March 2024)
Guidance focused on Recommendation 25 and trusts and similar arrangements, helping a finance company assess and mitigate risk where a trust or similar structure sits behind a customer.
FATF Guidance on Counter Proliferation Financing (February 2018)
Guidance on carrying out the financial provisions of Security Council resolutions against weapons of mass destruction proliferation, under which a finance company must screen and freeze without delay in line with Recommendation 7.
Guidance on Proliferation Financing Risk Assessment and Mitigation (June 2021)
Explains how a firm should assess and mitigate proliferation financing risk after the revisions to Recommendations 1 and 2, which brought proliferation financing within the risk assessment duty across the sector.
Guidance on Digital Identity (March 2020)
Helps a finance company decide whether a digital identity system is reliable and independent enough for customer due diligence under a risk based approach, which matters for the online channels through which deposits and loans are increasingly opened.
Artificial Intelligence and Deepfakes: Impacts on ML/TF/PF
A forward looking FATF scan of how artificial intelligence and deepfakes threaten preventive systems, for example, synthetic identities defeating the remote onboarding of a customer, alongside AI’s uses in screening and monitoring.
Money Laundering from Environmental Crime (July 2021)
A FATF study of how the proceeds of environmental crime are laundered through the financial system. Its relevance to a finance company is limited but real where a corporate borrower’s revenue may derive from illegal logging, mining or waste, and it adds to the red flags a lender weighs.
Trade Based Money Laundering, Private Sector Handout
A short FATF reference on the trade based money laundering typologies a private sector firm should recognise, such as mis invoicing and phantom shipments. It informs a finance company that funds a trade linked customer, sharpening the questions it asks about the underlying goods and payments.
Summary of Key Instruments
The table below distils the instruments a finance company relies on most, what type each is, whom it binds, and the core obligation it places on the firm. A quick reference to keep alongside you, not a stand in for the fuller sections above.
Instrument | Type | Binds | Core obligation for a finance company |
CDSA 1992 | Statute | Everyone | Report suspected criminal proceeds; do not tip off |
TSOFA 2002 | Statute | Everyone | Do not deal in terrorist property; screen and report |
FSM sanctions regulations (DPRK, Iran) | Regulations | All FIs | Freeze designated persons’ assets without delay |
MAS Notice 824 | Notice (binding) | Finance companies | Risk based CDD, wire transfer travel rule, records, STR |
Guidelines to Notice 824 | Guidelines | Finance companies | Primary guidance; how to meet the Notice |
Notice PS N01 / PS N10 | Notices | Payment services | Apply only where the firm also carries on payment services |
Finance Companies Act 1967 | Statute | Finance companies | Licence the firm; set the deposit and dealing limits |
FATF Recommendations | Standard | Countries/FIs | The global standard behind the domestic rules |
Conclusion
For a finance company in Singapore, the anti money laundering framework is real but proportionate, and it tracks the banking regime on a smaller scale. The criminal statutes establish offences and specific disclosure obligations relating to money laundering and terrorism financing. Applicable sanctions legislation establishes prohibitions, asset freezing requirements and other obligations concerning designated persons, property and activities. MAS Notice 824 and its Guidelines provide the principal AML/CFT framework applicable to finance companies. Because the money laundering risk lives mostly in cash and in corporate ownership, a finance company’s controls are built around who its customers are and how funds move through their accounts.
The instruments interlock. A finance company’s enterprise wide risk assessment draws on the national risk assessments; its due diligence and wire transfer work flows from Notice 824 and its Guidelines; its licensing obligations and the limits that keep it small and domestic come from the Finance Companies Act; and its sanctions and proliferation controls draw on the FSM Act sanctions regulations and the FATF standards. Seeing how the pieces connect is what turns a set of controls that merely exist into a framework a finance company can defend.
Frequently Asked Questions
MAS Notice 824 is the anti money laundering and countering the financing of terrorism notice for finance companies, issued under section 16 of the Financial Services and Markets Act 2022 and applying to firms licensed under section 6 of the Finance Companies Act 1967. It is read together with the Guidelines to Notice 824, which explain each obligation in turn.
A finance company takes fixed and savings deposits and lends to individuals and businesses, mainly through secured, domestic facilities such as hire purchase and housing loans. The Finance Companies Act stops it from offering current accounts repayable on demand by cheque, dealing in foreign currency, gold or precious metals, or holding foreign currency securities beyond limits, which is relevant to its lower relative money laundering risk.
Under Notice 824, a finance company performs customer due diligence when it establishes business relations, when it undertakes an occasional transaction above S$20,000, when it effects a cross border wire transfer above S$1,500 for a customer without an account, when it suspects money laundering or terrorism financing, or when it doubts information it already holds. It identifies and verifies the customer, any person acting for them, connected parties and beneficial owners.
Singapore’s 2024 money laundering assessment places finance companies in the lower risk band, citing a moderately lower ML threat and lower vulnerability because the sector offers a limited, straightforward product range and deals mainly with domestic customers. Cash handling is the main feature to watch, and the sector’s controls are assessed as being on a par with banks.
Yes. Notice 824 applies the travel rule, so a cross border wire transfer above S$1,500 must carry complete originator and beneficiary information, and the finance company must have procedures to obtain, keep and pass on that information and to handle transfers where it is missing.
Whenever it has reasonable grounds to suspect money laundering or terrorism financing. The finance company reports to the Suspicious Transaction Reporting Office, as a rule within five business days of forming the suspicion, and within one business day where sanctions are engaged. Our guide to STR red flags explains common triggers such as unusual cash or a transaction with no clear economic purpose.
About the Author

Pathik Shah
FCA, CAMS, CISA, CS, DISA (ICAI), FAFP (ICAI)
Pathik is a Chartered Accountant with more than 26 years of experience in governance, risk, and compliance. He helps companies with end-to-end AML compliance services, from conducting Enterprise- Wide Risk Assessments to implementing the robust AML Compliance framework. He has played a pivotal role as a functional expert in developing and implementing RegTech solutions for streamlined compliance.